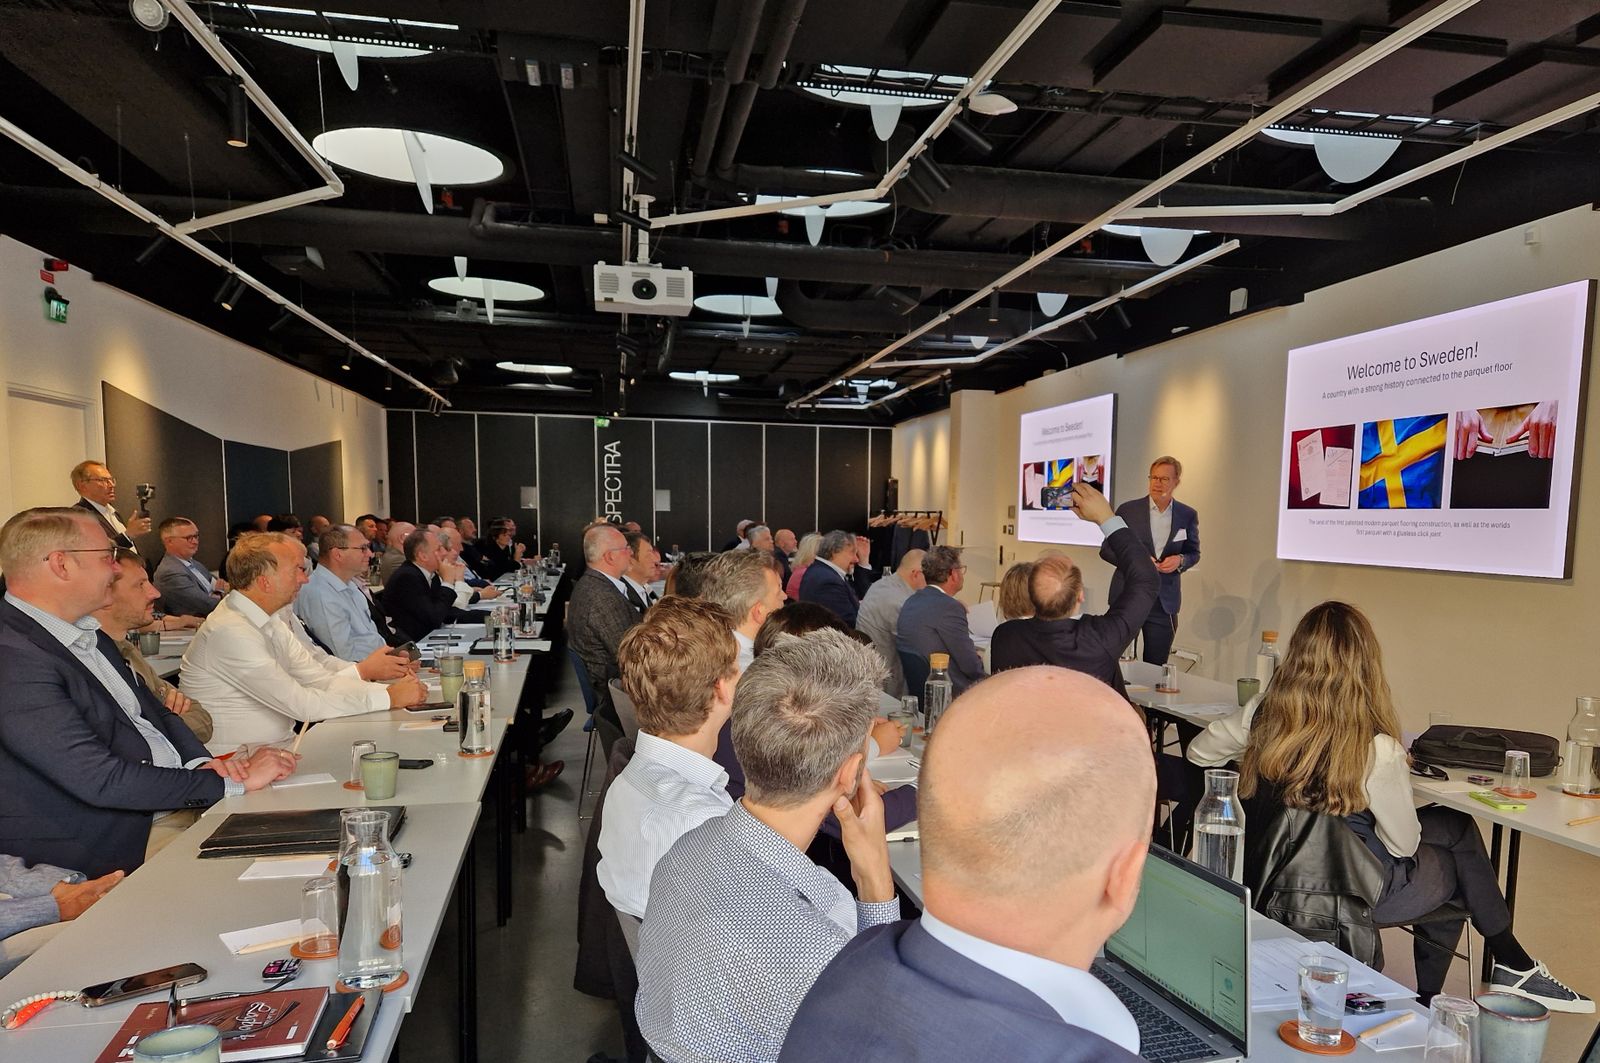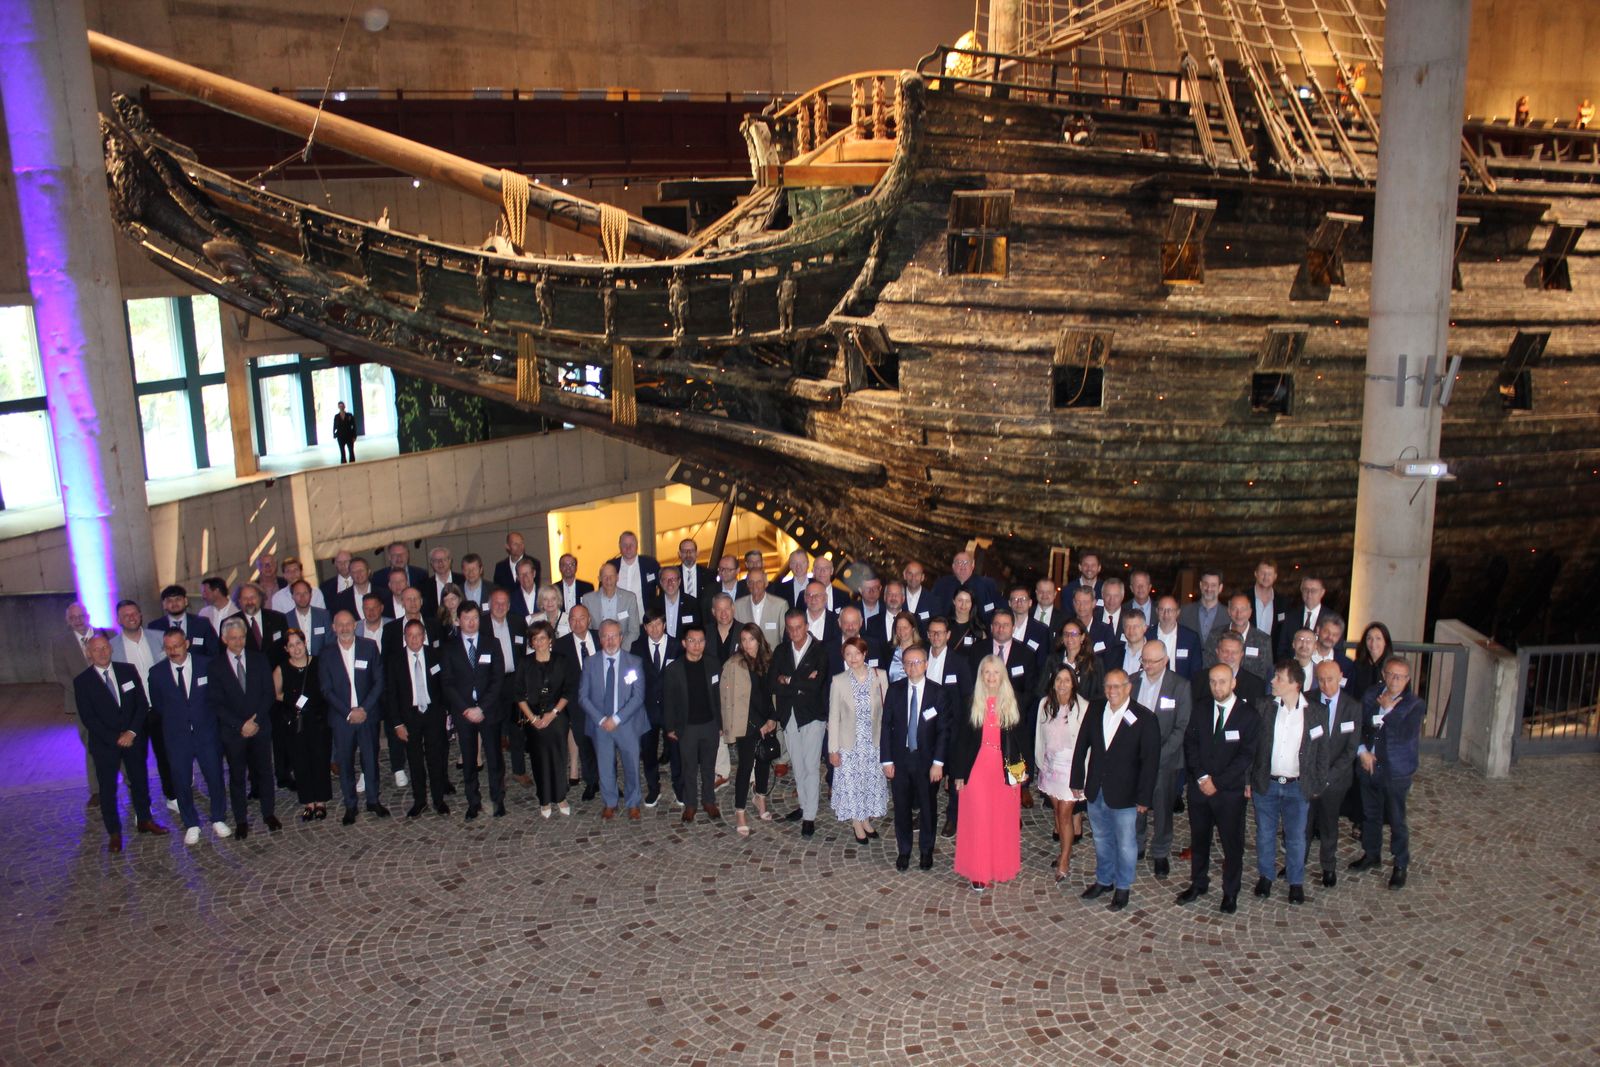
The Board of Directors of the European Parquet Federation (FEP) met in Paris on 20 October 2026 and reviewed the latest developments on European parquet markets.
While the first half of 2026 brought encouraging signs in several countries, the outlook has become more cautious since the summer. Across Europe, parquet markets are generally stable, with some regions recording moderate growth. However, geopolitical uncertainties, declining consumer confidence, rising savings rates, increasing labour and energy costs, and higher interest rates continue to weigh on investment decisions and construction activity.
The market situation remains highly fragmented from country to country. Several Members reported positive developments during the first semester, particularly in renovation and project business, but momentum weakened significantly during the third quarter. Consumers remain cautious, and spending priorities increasingly favour leisure and entertainment rather than home improvement.
At the same time, costs throughout the value chain continue to rise. Manufacturers face increasing prices for raw materials, labour and energy, while passing on additional costs to consumers remains difficult, especially when considering unfair competition from imported products from China and from new countries of origin with rapidly increasing volumes. Hardwood sourcing has become more challenging in certain regions.
Nevertheless, important opportunities remain for the parquet sector. In several countries, renovation activity and project business continue to provide stability and support demand.
Overall, the European parquet market can currently be characterised as stable but cautious. While signs of recovery are visible in some regions, economic and geopolitical uncertainties continue to limit confidence and investment decisions.
Read more here